Before you subscribe to land or a house
A structured checklist for verifying land, housing and estate purchase decisions in Nigeria.
Read article
A structured checklist for verifying land, housing and estate purchase decisions in Nigeria.
Read article
How to prepare for an initial affordability review before proceeding with a home-financing application.
Read article
A practical field checklist for comparing a property with its documents and marketing descriptions.
Read articleINSIGHTS / GROW
How to prepare for an initial affordability review before proceeding with a home-financing application.
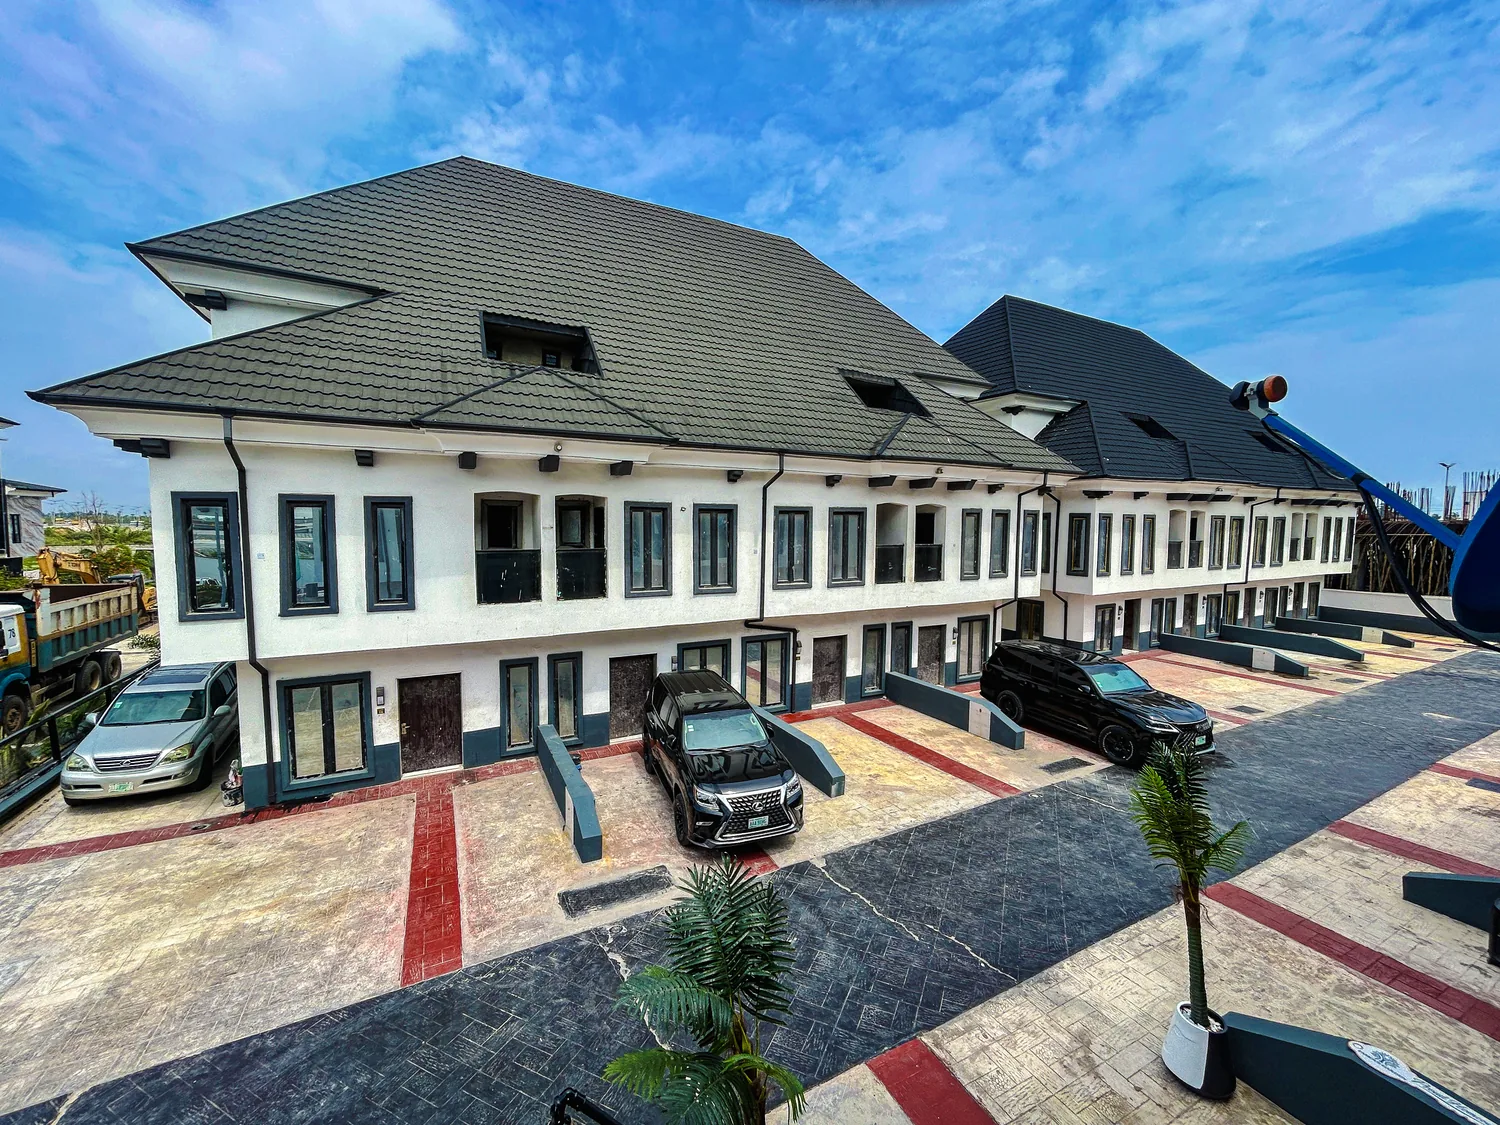
A completed residence shows the goal, not a guaranteed financing outcome. Before applying, compare documented income, debts, equity contributions and the full cost of an eventual mortgage.
Pre-qualification is an indicative screening based on information available at the time. It is not a loan approval, binding rate quote or promise of eligibility.
Consider income stability, existing loans, planned equity contribution, recurring household commitments and all costs beyond the purchase price.
Ask the proposed lender for current pricing and disclosure of application fees, insurance, legal charges, valuation costs and applicable taxes. A longer loan term may reduce monthly payments while increasing total borrowing costs.
A lender must independently evaluate credit, identity, affordability and the proposed property. Use Landshop Grow applications to organize the next steps, then rely on actual written lender documentation for final decisions.
An online mortgage calculator can help illustrate the relationship between principal, interest-rate assumptions, term and potential repayments. It cannot confirm a lender’s decision. Formal affordability review usually considers verified income, existing commitments, credit history, identity, proposed collateral and policy requirements that are not captured by an illustrative slider. The number a calculator produces should therefore be treated as a planning estimate rather than a guaranteed payment or a basis for making an unconditional property commitment.
Begin with reliable net household income and the expenses that recur even when nothing unusual happens. Include existing loans, household necessities, transportation, dependants, healthcare, insurance, utilities and the cost of maintaining the proposed home. Separate savings available for an equity contribution from money set aside for emergencies. A lower monthly payment achieved through a longer term may increase total borrowing cost, so compare realistic scenarios and consider the consequences of an interest-rate or income change.
Before relying on a quoted rate, ask whether it is fixed, variable, promotional or subject to review, and request the applicable written terms. Financing costs may include arrangement and legal fees, valuations, insurance, taxes and charges associated with the specific property. Understand the timing of disbursement, borrower conditions, what happens on missed payments and whether early repayment is allowed or carries a charge. Compare the total obligations, not only the headline rate.
A promising property may still require title checks, an acceptable valuation or additional approvals before a lender can proceed. Keep property information aligned with the application: the current seller, address, price, unit reference, development stage and supporting records. Ask the lender or authorized intermediary which conditions must be satisfied before a decision becomes binding. Landshop’s Grow pathways can organize the enquiry, but the final financing decision and enforceable terms belong to the relevant authorized provider.
Join the discussion.
Read approved comments and share your perspective. Submissions are reviewed before appearing publicly.
Loading comments…